
Medical practice insurance
Insurance for the clinical work
and the business around it
A medical practice has two responsibilities running at once: caring for patients and keeping the clinic behind that care working. We learn how your providers, staff, equipment, systems, and space depend on one another, then build around the problems that could interrupt care or put the business you built at risk.
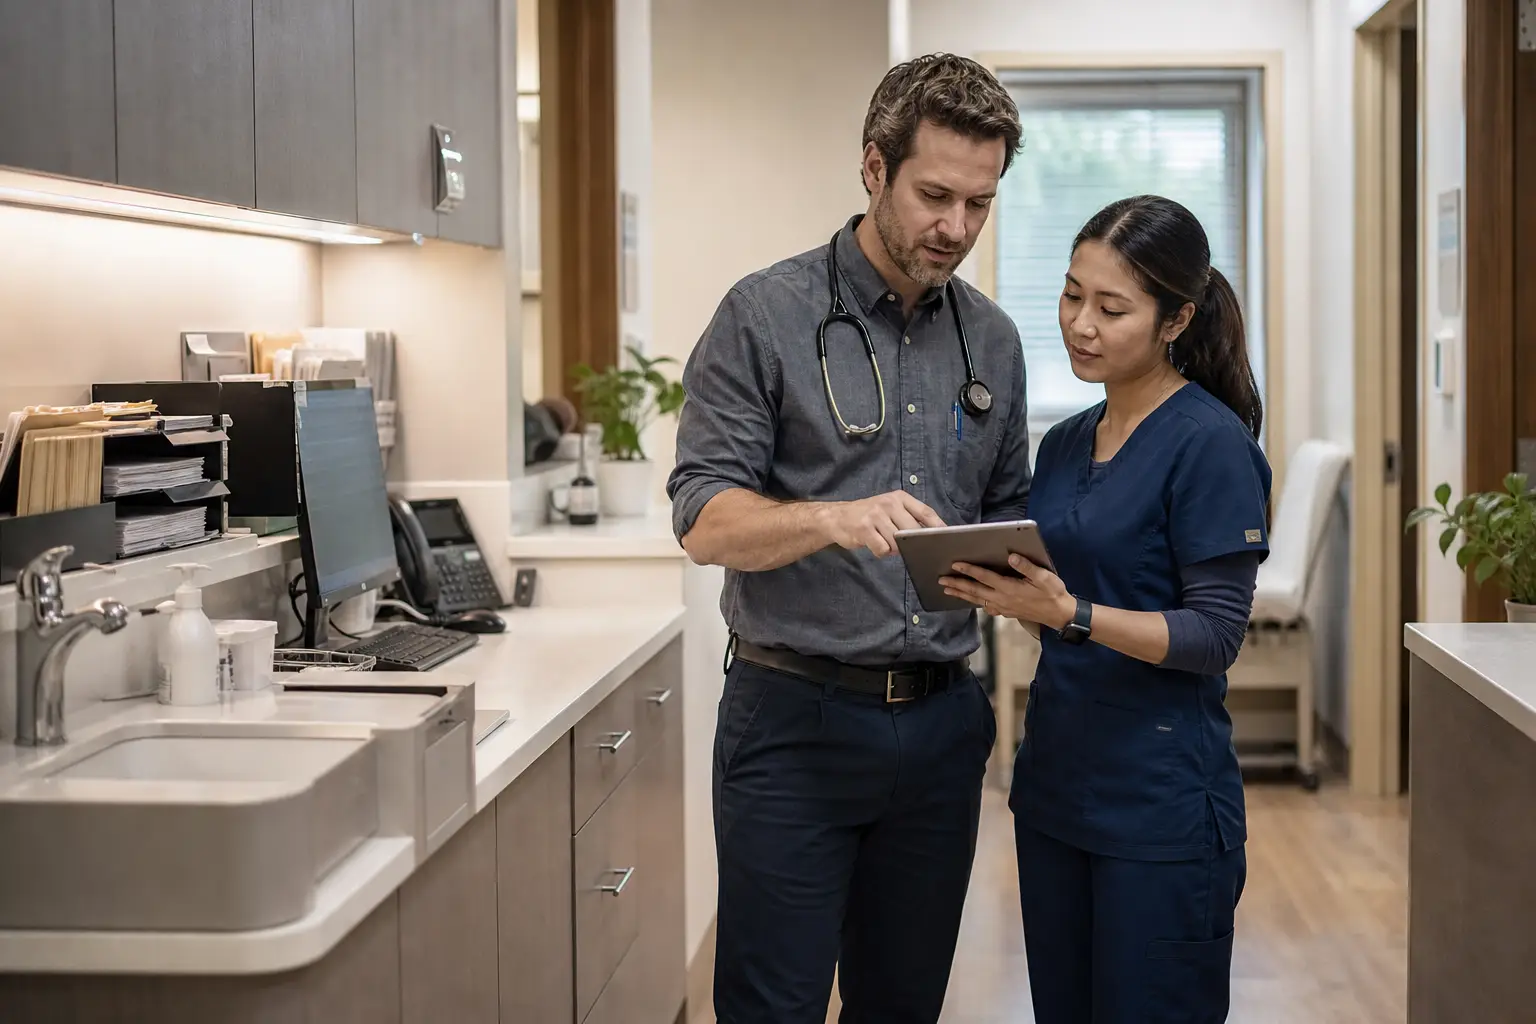
Inside the practice
What makes a medical practice different?
Patient care and the business that supports it happen under the same roof. Adding a provider, bringing a procedure in-house, buying specialized equipment, storing medications, or depending on one system for scheduling and records can change more than it first appears. We start with how the clinic actually works and what would be hardest to put back together after a bad day.
- 01
Medical malpractice
A claim can question a diagnosis, a treatment decision, the follow-up, the documentation, or what a patient says should have happened. The coverage needs to follow the clinicians and the work actually being done.
- 02
General liability
Not every problem is about patient care. Someone can slip in the waiting room, an employee can damage property away from the clinic, or an ordinary accident can turn into a demand for payment.
- 03
Property and equipment
An exam room is hard to use without the equipment inside it. We look at what the clinic owns, what it would cost to replace, and which items could keep you from seeing patients if they were damaged.
- 04
Business income
A closed clinic can still have payroll, rent, loan payments, and patients who need somewhere to go. This is the part that can buy the practice time to recover after covered damage interrupts the workday.
- 05
Cyber and breach response
A locked system or exposed patient record becomes an operational problem immediately. The clinic needs experienced people who can investigate, restore access, guide notifications, and help the team keep moving.
- 06
Workers compensation
Your team lifts, bends, handles sharps, moves equipment, and spends long days on its feet. When someone gets hurt doing the work, both the employee and the practice need a clear path forward.
What we need to understand
What should an advisor know about your clinic?
The name on the front door tells us very little. Two clinics in the same specialty can have different providers, procedures, equipment, contracts, systems, and tolerance for being closed. Those details are where a plan either starts to fit the practice or quietly misses it.
Six details that tell us how the clinic really works.
- 01
The people delivering care
Owners, employed physicians, advanced practice providers, and contractors may work side by side without having the same relationship to the business. The setup should reflect who is actually treating patients.
- 02
Services and procedures
A clinic changes when it adds procedures, expands a specialty, dispenses medication, or brings work in-house. Yesterday’s description of the practice may no longer fit what happens there today.
- 03
The work that came before
Malpractice claims can arrive long after the appointment. Prior-acts dates, reporting rules, and tail coverage decide whether earlier clinical work follows a provider through a move or ownership change.
- 04
When the systems go down
The first question after a cyber event is usually not “is this covered?” It is “how do we see tomorrow’s patients?” The response plan matters as much as the eventual reimbursement.
- 05
How replaceable the equipment really is
The invoice price is only part of the problem. Delivery time, installation, calibration, spoiled medication, and the loss of a room or service can matter just as much after equipment fails.
- 06
How long the clinic can stay closed
A short interruption is inconvenient. A longer one can scatter patients, strain the team, and disrupt referral relationships. The plan should reflect how quickly the clinic could realistically reopen.
Medical practice insurance questions
What insurance does a medical practice usually need?
A medical practice needs a plan for both patient care and the business around it. That means thinking through malpractice allegations, injuries inside the office, damaged equipment, stolen or locked patient data, employee injuries, and a closure that interrupts revenue. The mix should follow how the clinic actually operates.
Does general liability cover medical malpractice?
No. A patient saying care caused harm is a medical malpractice issue. General liability handles ordinary accidents that are not about clinical judgment, such as someone slipping in the waiting room. A clinic usually needs both because the same day can create very different kinds of problems.
Does an independent medical practice need cyber insurance?
It is worth serious consideration. A breach, ransomware event, or unusable system can stop scheduling, billing, and access to patient records while creating legal and notification work. Useful cyber coverage is not just a reimbursement check; it gives the clinic experienced people to call when the problem begins.
When should a medical practice review its insurance?
Review it before every renewal, and sooner when you add a provider, procedure, location, piece of major equipment, ownership partner, or important contract. Those changes can quietly outgrow the current setup. Starting early gives you time to solve the problem instead of discovering it during a claim.
Let’s understand the clinic before we recommend anything.
Tell us how care is delivered, what keeps the day moving, and what you cannot afford to have interrupted. We will build from there.